

A car crash or a bad fall can look minor at first, but the bills that follow often tell a different story. Many Charlottesville families expect a scraped knee or a sore neck to heal in a week, only to face months of treatment and missed paychecks instead. Virginia law gives injured people a path to recover money for these costs, but that path comes with real risks and firm deadlines. Understanding how an everyday accident turns into a long-term financial strain helps families make smarter choices from day one.
Why a Small Accident Can Create a Big Financial Problem
A rear-end crash at 15 miles per hour or a slip on a wet floor rarely feels like an emergency at the moment it happens. Adrenaline can mask pain for hours, and many people go home instead of to the emergency room. By the time the stiffness sets in the next morning, some families have already lost the chance to connect their injury clearly to the accident, which is often where a Charlottesville personal injury lawyer helps sort out what records still support the claim.
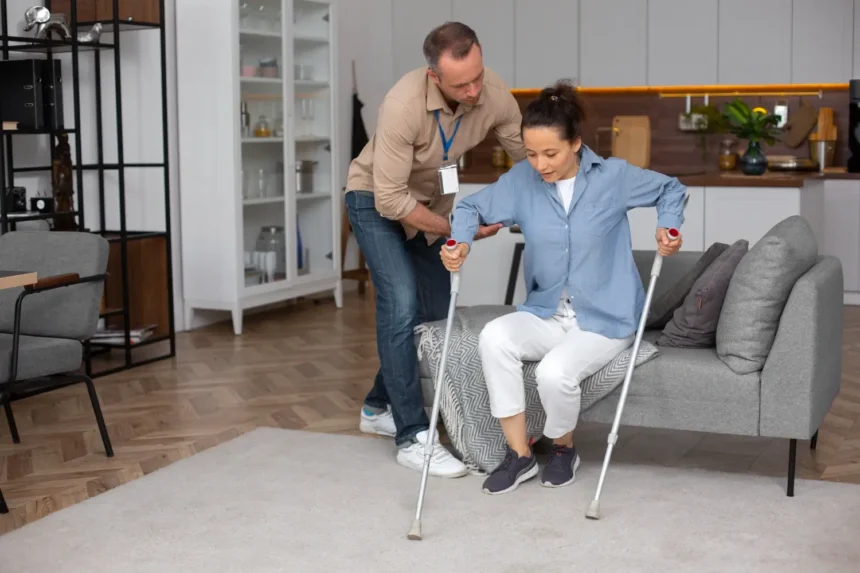
What looks like a one-time doctor visit can turn into weeks of physical therapy, follow-up scans, and prescriptions that were never part of the original plan. Meanwhile, missed shifts at work add up just as fast as the medical bills do. A minor accident and a major financial setback are often only a few bad decisions apart.
How Medical Bills and Lost Wages Add Up Over Time
The first bill from the emergency room rarely tells the whole financial story of an accident. Follow-up visits, imaging, medication, and therapy sessions all arrive separately over the following weeks and months. For anyone who cannot work during recovery, a missing paycheck often hurts just as much as the medical costs themselves.
- ER visit – initial exams, imaging, and stabilization costs
- Physical therapy – weeks or months of ongoing treatment sessions
- Lost wages – missed shifts and reduced work hours
- Home help – paid help for tasks you used to do
Why Virginia’s Insurance Minimums Often Fall Short
Many drivers in Charlottesville carry only the minimum insurance the state requires, and that minimum often falls short of a serious injury’s real cost. A single visit to an emergency room after a bad crash can burn through thousands of dollars before any physical therapy even starts. Once the at-fault driver’s policy runs out, the injured family is left looking for another source of money.
Under Virginia Code § 46.2-472, every driver’s policy must carry at least $50,000 per injured person and $100,000 per accident, which sounds like a lot until it is split among a hospital stay and months of lost income. Virginia also requires insurers to offer underinsured motorist coverage that matches a driver’s own liability limits under Virginia Code § 38.2-2206, unless the driver rejects it in writing. Checking your own policy for this coverage before an accident happens can prevent a financial gap later.
Why One Mistake Can Cost You the Whole Claim
Virginia follows one of the strictest fault rules left in the country, and it can turn a strong claim into nothing. Under this rule, called contributory negligence, a person found even slightly at fault for their own accident can be barred from recovering any money at all. Insurance companies know this rule well and often look for any small detail that lets them shift blame onto the injured person.
This is why the story you tell at the scene, and the words you use with an insurance adjuster, matter so much in Virginia. A careless comment like “I did not see them coming” can become the reason a claim gets denied months later. Sticking to simple facts and avoiding guesses about fault protects a family’s financial recovery.
What Families Can Do Before Time Runs Out
Every dollar owed for an accident becomes harder to collect the longer a family waits to act. Under Virginia Code § 8.01-243, most injured people in Virginia have two years from the date of the accident to file a lawsuit, while property damage claims get five years. Waiting even a few months to gather proof can mean losing access to camera footage, witness memories, or repair estimates.
- See a doctor – even for injuries that seem minor
- Keep records – save bills, notes, and missed workdays
- Track income loss – compare pay stubs before and after
- Note the deadline – mark the two-year filing date on a calendar
What Long-Term Recovery Really Depends On
Financial recovery after an accident rarely follows a straight line. It depends on quick medical care, careful records, honest conversations about fault, and a clock that keeps ticking whether a family is ready or not. Charlottesville households that treat these pieces as connected, rather than separate problems to solve one at a time, tend to come out of a hard year in better financial shape. Protecting the ability to pay for a long recovery matters just as much as the healing itself.